Business Role
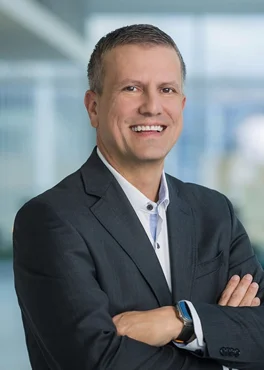
Harry Sideris is Duke Energy's current President and CEO. He took the role on April 1, 2025 after nearly three decades inside Duke, including leadership roles across customer operations, regulated utilities and enterprise operations. [S8]
His strategic importance is that he inherited a company whose core problem had changed. Duke was no longer planning around flat or modest electric demand. AI data centers, advanced manufacturing and population growth were creating multi-gigawatt incremental load requests while the company was simultaneously retiring coal and modernizing the grid.
Business Context
Sideris inherited five simultaneous constraints:
Strategic Bets
- Expand the regulated capital plan to about $103B while preserving the 5%-7% adjusted EPS growth framework.
- Use Electric Service Agreements and large-load protections so data-center projects help rather than strand costs on existing customers.
- Maximize the existing nuclear fleet while preserving new-nuclear site and technology options.
- Add gas, solar, storage, hydro and grid capacity rather than betting the system on one replacement technology.
- Use the Brookfield Florida minority investment, Piedmont Tennessee sale and capital markets to reduce financing pressure.
- Complete the DEC/DEP legal combination while preserving state-specific regulation.
Why Those Decisions Matter
Utility leadership is a capital-allocation and regulatory-coordination job. Decisions can change generation mix, customer bills, debt/equity needs, reliability, environmental obligations and the regional capacity available for economic development.
Assets approved today can remain in service for 30–80 years.
Strategic Tension
The central tension is timing. Duke must build generation and grid infrastructure before much of the new load is fully realized, but building too much too early would raise customer bills and weaken credit metrics.
Sideris therefore has to make long-horizon investments using forecasts that can change faster than utility construction schedules.
Capital Allocation Lens
A successful regulated-utility leader cannot maximize one variable permanently at the expense of the others. The regulatory compact depends on maintaining balance.
What to Watch
The clearest scorecard is operational and regulatory, not promotional:
- secured load converting into actual demand;
- capex entering rate base on schedule;
- rate-case outcomes;
- customer bill growth;
- FFO/debt and financing needs;
- new generation project schedules;
- DEC/DEP integration;
- adjusted EPS growth.
The most important question is whether Duke can turn unprecedented load demand into durable, customer-supported regulated earnings rather than simply a larger construction budget.
Evidence
Operating Mandate
Sideris is effectively managing a capacity-cycle turnaround in reverse: Duke is not trying to shrink excess assets; it is trying to build enough assets fast enough without losing the discipline of a regulated utility.
The mandate can be written:
Financing Decision
The Brookfield and Piedmont transactions demonstrate a willingness to recycle ownership value rather than fund everything with common equity. That is a major capital-allocation signature of the Sideris era.
New Nuclear Decision
Sideris also faces a decision that can define Duke for decades: whether, where and when to commit to new nuclear. The correct decision depends on load certainty, technology readiness, federal policy and cost sharing—not on a single corporate emissions target.