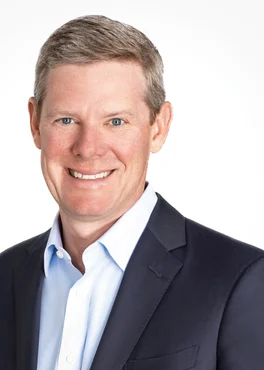
1. Business Role
President before CEO
McInerney was responsible for Visa's global businesses as president.
The succession announcement describes oversight across market teams, business units, product, merchants and client services.
He therefore entered the CEO role with experience across the existing organization, not as an outsider introducing its first digital strategy. [S25]
Corporate operator
As CEO, he leads the organization supplying a network and services to institutions with their own customers and priorities.
A bank wants its payment products to work. A merchant wants useful acceptance at an acceptable cost. A processor or fintech can need capabilities supporting several networks.
Leadership involves making those relationships work commercially, not running a single Visa-owned consumer bank.
2. The Business He Inherited
A mature core
An already broader portfolio
The starting constraint
The opportunity was to make more of that infrastructure useful to clients.
The difficulty was that a wider portfolio contains different buyers, technology and operating models.
A card-network contract does not automatically win a core-banking migration or a separate fraud-service purchase.
The inherited advantage was reach and existing relationships. The remaining task was usable integration and new client value.
3. Business Thesis
Serve more than consumer card purchases
Visa's stated growth priorities combine consumer payments, commercial and money movement, and value-added services.
McInerney repeated those priorities in the July 2026 earnings statement. [S2]
The business implication is broader institutional relevance.
A client may pay Visa to solve a processing, risk or money-movement problem even where the activity is not another ordinary Visa card purchase.
Make capabilities separately usable
At the 2025 Investor Day, McInerney described unbundling Visa capabilities for a broader range of clients and payment flows. [S98]
The mechanism is selling a useful component or service around infrastructure, rather than requiring every customer to buy an identical whole system.
That thesis must pass a practical test.
A separately offered capability needs its own customer proposition, implementation and economics. A larger catalog alone does not demonstrate a stronger business.
4. Strategic Bets
Bet 1 — Give growth businesses fuller operating ownership
At Investor Day, McInerney said he created an operating model with leaders reporting directly to him across major growth areas, backed by product, engineering and go-to-market teams. [S98]
The problem was execution across different businesses.
A services or money-movement proposition needs more than sponsorship from the core network organization. It needs people accountable for building and selling it.
The mechanism was organizational: connect responsibility with the teams required to deliver.
The risk is fragmented execution if the businesses become separate catalogs rather than useful parts of one client relationship.
The reported organizational change establishes a management choice, not proof of every eventual product's return.
Bet 2 — Add institutional operating capabilities
Pismo completed in January 2024 and Featurespace was reported complete in December 2024.
They added banking/processing software and behavioral-fraud technology during his CEO period. [S12][S14]
The businesses address different client jobs.
Buying them can broaden the problems Visa can solve, but also adds integration and operating work.
These are leadership-period company commitments. The transaction releases do not establish that McInerney personally designed every platform or originated every deal.
Bet 3 — Build deeper local infrastructure
The 2026 Prisma and Newpay purchases added Argentine issuer-processing and domestic payment infrastructure.
The mechanism was acquiring established capabilities serving local institutions, not simply issuing more consumer cards.
The result was completed ownership of the specified businesses.
Whether integration produces durable commercial returns remains a further question.
Bet 4 — Extend infrastructure into new interfaces
Intelligent Commerce and the Stablecoin Platform address different changes in payment interaction.
The October 2026 agent pilot executes approved business payments. The July stablecoin launch began with selected beta access. [S22][S51]
The common strategic connection is keeping Visa useful beneath evolving interfaces.
The risk is treating an interesting demonstration as a mature client business.
The evidence establishes different development stages, not a completed universal transition.
5. How Those Bets Changed the Business
Product
The portfolio adds operating software, risk capabilities and new payment interfaces around the existing network.
It does not replace the network with one new product.
Customer
More client decisions can concern institutional operations rather than the selection of a card brand.
That broadens the potential buyer inside an existing customer organization.
Revenue logic
Services can earn revenue for solving a particular client problem.
Visa still reports one Payment Services segment; its growth priorities are not three separate reportable divisions. [S1]
Distribution
Existing institutional relationships can help introduce additional capabilities.
They do not eliminate the need to earn the separate service purchase.
Moat
The potential advantage combines reach, expertise and useful implementation.
That advantage remains conditional on clients finding the service worthwhile after costs and incentives.
Industry position
The company can participate across more payment systems.
Its role becomes broader than a single rail without becoming ownership of the entire financial system.
6. Resource Allocation
Acquisition capital
Prisma and Newpay required combined cash consideration of $1.5 billion.
That is one observable allocation to the two businesses together, not $1.5 billion for each. [S3]
The amount establishes commitment. It does not establish the final return.
Product and engineering capacity
The operating model described by McInerney places fuller teams behind the growth businesses. [S98]
This allocates talent and management attention as well as money.
Client economics
Visa also commits resources through client incentives.
Those arrangements can support participation while reducing retained revenue under the applicable accounting. [S1]
The management question is what durable activity and service value the commitment produces.
Operating trust
Reliability, institutional risk and implementation remain necessary while the portfolio grows.
New services cannot compensate for a core relationship that clients no longer trust to work.
7. Business Model: Before vs. After
| Dimension | At the 2023 succession | By the October 2026 research cutoff |
|---|---|---|
| Value created | Network connectivity plus established services | Broader operating capabilities around the core |
| Core product | Payment network and existing digital/service portfolio | Same core with additional software, risk and interface capabilities |
| Buyer | Institutions and merchant-side participants | Those relationships plus more distinct operating-service decisions |
| User | Cardholders, merchants and institutional teams | Additional client teams using the expanded capabilities |
| Revenue logic | Network activity and services | Continued activity plus wider service opportunities |
| Software role | Already important | Further processing, banking and risk platforms added |
| Distribution | Established participant and partner relationships | More capabilities offered through those relationships |
| Scale | Mature international system | Continued scale, with newer products still at different readiness stages |
| Company boundary | Already included Tink and Currencycloud | Added Pismo, Featurespace, Prisma and Newpay |
This is an incremental expansion, not a false contrast between a card-only company in 2023 and a fully transformed universal platform in 2026.
8. What Worked / What Didn't
Completed capabilities and bounded operating progress
A purchase route that did not proceed
Core economics and legal scrutiny remain
Q3 fiscal 2026 net revenue was $11.633 billion, while reported results also included severance and litigation items. [S2]
Growth does not isolate the CEO's personal contribution or demonstrate that every allocation worked.
The DOJ's 2024 debit complaint is a separate allegation-based legal matter, not a personal finding against McInerney. [S61]
9. Business Legacy
McInerney's tenure is ongoing.
The clearest structural development is an organization pursuing broader service and money-movement businesses alongside the core network.
A lasting result would be capabilities that clients continue to choose because they work together and solve distinct problems.
That remains a test, not a settled final legacy.
The changes are built by Visa's teams, acquired businesses, clients and partners. Corporate leadership is important without becoming sole authorship of every product or result.
Career Background
McInerney previously led JPMorgan Chase's consumer-banking business and worked in McKinsey's retail-banking and payments practices.
That experience is relevant to understanding institutional customers and operating businesses.
It does not make Visa's network model identical to consumer banking. [S24]
Career Timeline
- 2013: joins Visa as president.
- 2014: Token Service launches during his presidency.
- February 2023: becomes CEO.
- 2024: Pismo and Featurespace enter the portfolio during his CEO tenure.
- February 2025: publicly describes the operating model and broader service strategy.
- February 2026: Prisma/Newpay complete; the proposed Prosa purchase is denied.
- October 2026: Visa announces the bounded BILL/Billtrust live pilot.
These are role and tenure milestones, not proof of personal invention.
Common Misconceptions
“He founded Visa.”
He became CEO of an established business after serving as president.
“The expanded services portfolio began only in 2023.”
Major digital capabilities and acquisitions predated the succession.
“Every transaction during his tenure was his personal design.”
Company releases establish institutional work and leadership accountability, not sole technical authorship.
“Every announced growth initiative is already a mature business.”
Preparatory approvals, beta access and live pilots have different meanings.
“He is also the current board chair.”
The company's CEO and independent chair roles are distinct in the governance evidence. [S4]
Evidence
- [S24], [S25], [S4] Role, career and governance.
- [S98] The directly described operating model and capability strategy.
- [S11]–[S14] Inherited versus later acquired capabilities.
- [S6]–[S9], [S3] Argentine capital commitment and the denied Prosa route.
- [S21], [S22], [S51] Product initiatives with actual readiness boundaries.
- [S1], [S2], [S61] Reporting and constraint context.
- [S62] The digital-credential history predating the CEO appointment.